
Who We Help · Vape & Smoke Shops · Bookkeeping
Vape shop bookkeeping: excise duty in your cost, and stamps that have to match
A vape and smoke shop carries most of its tax exposure inside the inventory itself, not on a separate tax line. Federal vaping excise duty, and since July 2024 an additional Ontario duty on top of it, are already built into every unit before it reaches your shelf. The bookkeeping job is tracking that embedded cost accurately and matching stamped product to the province it can legally be sold in. It also means keeping the cash side clean enough that CRA has no reason to look twice.
By the AnalytIQ Accounting team · Last reviewed: September 12, 2026
At a glance · vape and smoke shop owners
Not sure which applies to you? Get a free proposal or book 15 minutes.
Excise duty is baked into your cost — book it that way
Since October 2022, vaping products made or imported into Canada have carried a federal excise duty. It is applied per millilitre of vaping substance and paid by the licensed manufacturer or importer before product reaches a retailer. Since July 1, 2024, Ontario is one of the provinces that entered a coordinated vaping duty agreement with the federal government. That agreement adds an equivalent provincial duty on top, which roughly doubles the combined excise embedded in product sold in Ontario compared with a non-participating province. None of this is a line you remit; it is already inside your invoice cost. That means your cost of goods sold silently carries a tax rate that changes if a supplier's product mix shifts between smaller and larger container sizes. This happens because the duty is calculated per millilitre in tiers rather than as a flat percentage.
Most shops in this niche also carry traditional tobacco — cigars, rolling tobacco, papers, and shisha. That product line runs on its own older tax regime: federal excise duty and Ontario tobacco tax, also embedded upstream in wholesale cost. Your side of the paperwork here is an Ontario tobacco retail dealer permit rather than any duty remittance. We keep vaping and tobacco as separate categories in the chart of accounts rather than one blended "smoke shop" line. The duty regimes, the stamp rules, and the regulatory risk each product line carries are genuinely different. A blended margin number hides which side of the store is actually driving profit.
Stamps matter as much as SKUs
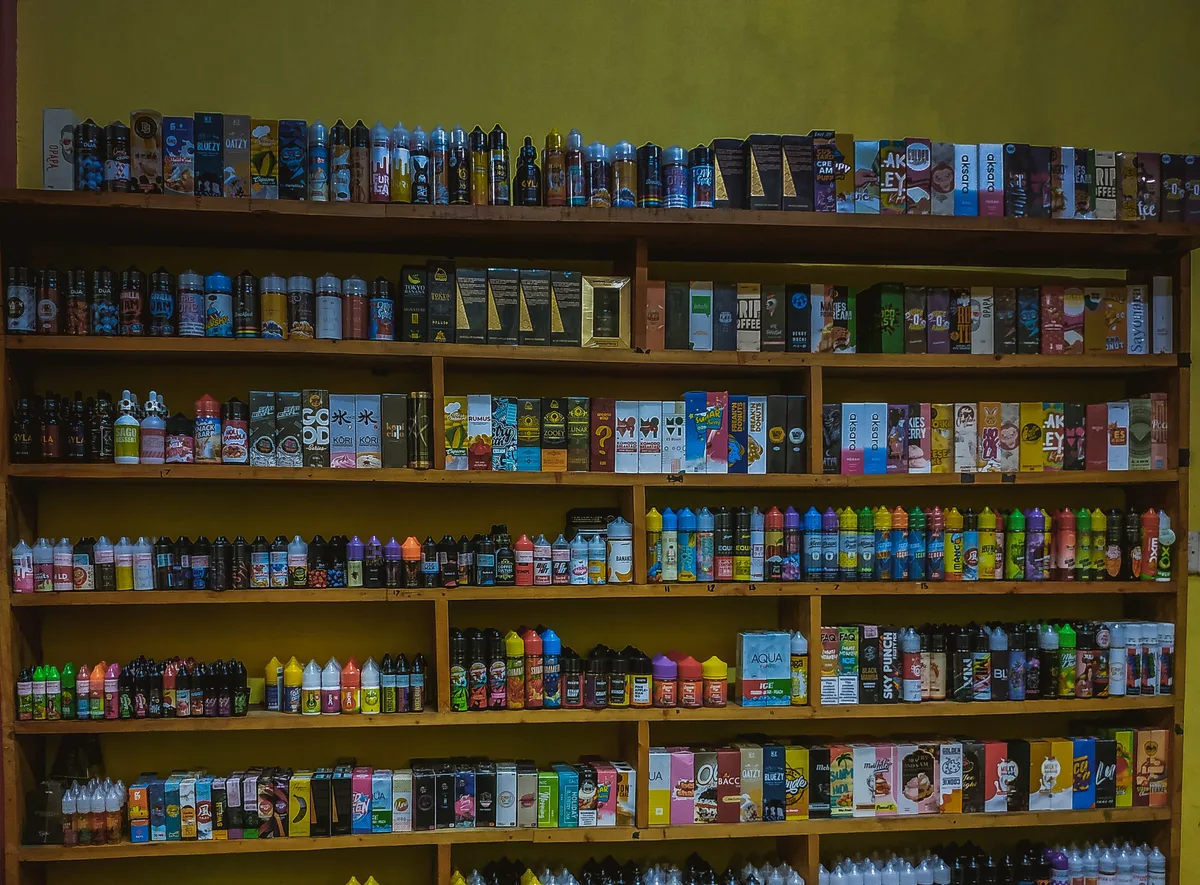
Every legally sold vaping product carries an excise stamp. The stamp series differs for a coordinated province like Ontario versus a non-participating one. A product correctly stamped for sale in Ontario is not necessarily legal to sell in a province that never joined the coordinated agreement. The reverse is also true. A shop with more than one location, or one that fields online orders shipping across provincial lines, needs inventory tracked by stamp series alongside the usual SKU. That matters because a receiving error here is a compliance problem, not just a bookkeeping one. We tag incoming stock by stamp type at receiving so a stamp mismatch is caught before it reaches the shelf, not after a compliance visit finds it.
| Layer | Who pays it | Where it shows up in your books |
|---|---|---|
| Federal vaping duty | Licensed manufacturer or importer | Embedded in your purchase invoice cost |
| Ontario coordinated additional duty | Same licensed party, on Ontario-stamped stock | Also embedded in cost — pushes Ontario product cost above non-participating provinces |
| HST | You, at the register | Charged on the full shelf price, duty already included |
Cash, age verification, and the daily close
Vape and smoke shops run cash-heavy, age-restricted sales in a category the CRA has flagged for retail-sector attention. The daily close carries a bit more discipline than an ordinary specialty shop. That means a counted float at open and close, deposits made intact, and a cash-over/short log by shift, so a pattern shows up while it is still small. Age verification failures are a compliance risk separate from bookkeeping. The record of who staffed a given shift matters if a mystery-shop or inspection ever names a specific transaction. Till assignments by staff member are worth keeping alongside the cash log, not just the sales total. A POS built for age-restricted retail, prompting for an ID check on every applicable SKU, gives you both the compliance record and a clean sales feed at once. That's worth more here than a generic system that treats every product the same way.
When a product ban turns inventory into a write-off
Flavour restrictions and other product-specific rules have changed the assortment more than once since the category was regulated. A shop holding stock of a line that becomes non-compliant needs that inventory moved out of saleable stock immediately. That means a documented reason and date, rather than letting it quietly age on a shelf report. Keeping a running note of regulatory changes affecting specific product lines, tied to the inventory system, turns a sudden ban from a scramble into a routine write-off. That write-off is then supported by a paper trail. The daily reconciliation habits above feed directly into the tax filings covered on our vape shop tax services page. The ongoing monthly close is what our bookkeeping services are built around.
What we take off your plate
Bookkeeping for vape and smoke shop owners, handled.
- Federal and Ontario vaping duty tracked as embedded cost, not a tax line
- Excise-stamped stock reconciled by province before it reaches the shelf
- Monthly reconciliations in QuickBooks Online or Xero
- Receipts captured through Dext, nothing typed twice
- GST/HST filed from clean books, on time
- Year-end financials ready for the T2 without a clean-up
Mistakes we fix
Three things that go wrong for vape and smoke shop owners.
- Booking excise duty as a separate tax line instead of the embedded cost sitting in every unit
- Letting the tobacco and vape retail permit lapse and not noticing until a whole category cannot be sold
- Leaving banned or delisted stock on the books at full cost instead of writing it off when the ban lands
Recognise one? Book a call and we will tell you what it is costing you.
Services for vape and smoke shop owners
Six services, one team that knows how vape and smoke shop owners run.
Start with one. Add the rest when it makes sense; the books, payroll and tax already talk to each other.
Free proposal
A fixed fee for your bookkeeping, in writing.
- Tell us about your business. The form takes about a minute.
- A short discovery call. Fifteen minutes to confirm what you need.
- A fixed fee in writing. We reply within one business day. No hourly surprises.
- Canadian and US filings under one roof
- Cloud-first: QuickBooks Online, Dext, Wagepoint
- Brampton, Ontario, with clients across Canada and the US
Related answers
Browse all 200 answers.
Common questions.
Do we need to remit vaping excise duty ourselves?
No — the federal duty and Ontario’s coordinated additional duty are paid by the licensed manufacturer or importer and arrive already embedded in your purchase invoice cost. Your job is tracking that cost accurately, not remitting the duty yourself.
Why does the excise stamp matter for bookkeeping, not just compliance?
The stamp series differs between Ontario and non-participating provinces. That means inventory has to be tracked by stamp type as well as SKU if you sell across provincial lines. A stamp mismatch caught at receiving is a bookkeeping fix; one caught during an inspection is a compliance problem.
How should we handle stock affected by a new product ban?
Move it out of saleable inventory immediately with a documented date and reason, rather than letting it sit on the shelf report. A running note tied to your inventory system turns a sudden regulatory change into a supportable write-off instead of a scramble.
Related reading
Books that match the stamp on every unit.
Book a consultation and get a plain answer on exactly what applies to you.